
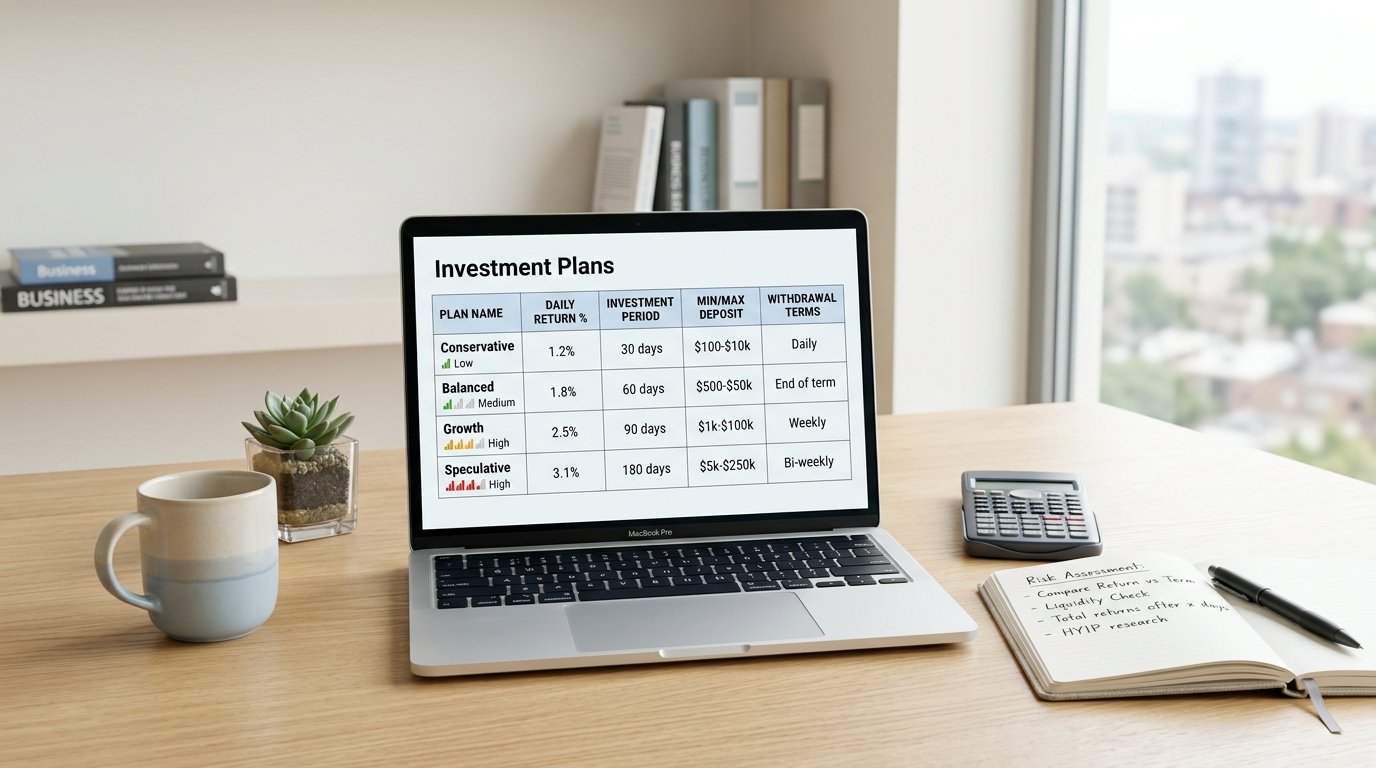
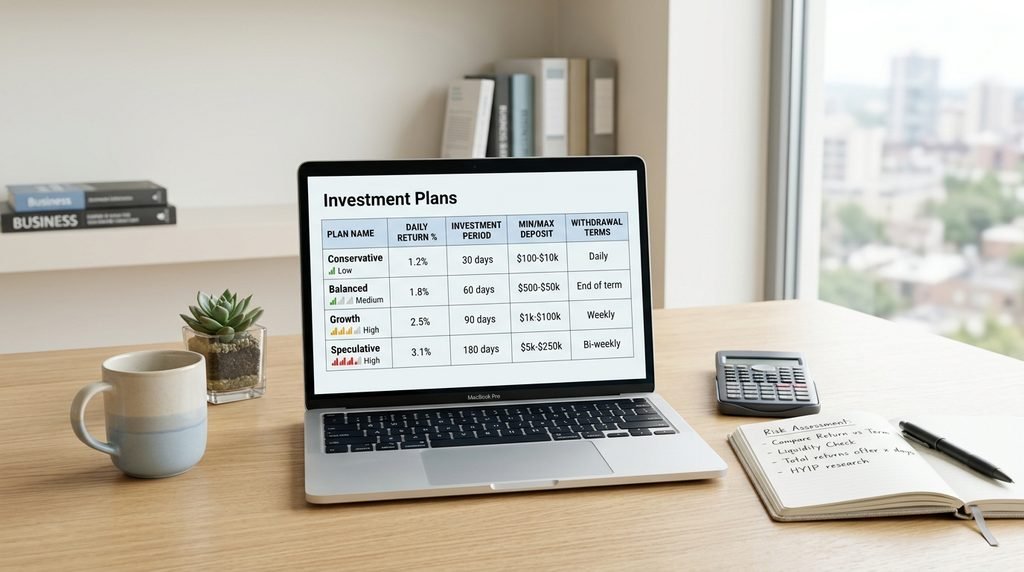
HYIP websites often present their investment plans in a simple table. You may see daily percentages, minimum deposits, maximum investment amounts, and fixed payout periods. At first glance, these details can make a program look easy to understand.
However, reading an investment plan is about more than comparing percentages. You also need to understand what the numbers mean, which conditions apply, and what risks may be hidden behind the advertised returns.
This guide explains how to read HYIP investment plans and identify important details before making a financial decision.
What Is a HYIP Investment Plan?
HYIP stands for High-Yield Investment Program. These online programs advertise unusually high returns over relatively short periods.
A typical HYIP plan may specify a minimum deposit, a promised daily or weekly return, an investment duration, and rules for withdrawing funds. Some programs also advertise referral commissions or bonuses for larger deposits.
The main concern is that advertised returns do not prove that a program generates enough legitimate income to pay investors. Some HYIPs may use money from newer participants to pay earlier participants, while others may stop paying without warning.
For this reason, an investment plan should be treated as a set of advertised terms, not proof of a sustainable business.
1. Understand the Advertised Return
The first number most people notice is the percentage return. A plan might advertise 2% daily, 20% weekly, or 100% after a fixed period.
These figures are not directly comparable unless you understand how they are calculated.
For example, a plan advertising 2% daily might mean:
- Return on the original deposit: The advertised percentage is calculated using the initial amount.
- Compound returns: Earnings are reinvested, potentially increasing the amount used for later calculations.
- A total return over a fixed period: The percentage applies to the entire investment term rather than each day.
Always look for an explanation of the calculation method. If the website does not clearly explain how returns work, that uncertainty is a warning sign.
Also remember that an advertised rate is not the same as a verified or guaranteed profit.
2. Check the Investment Duration
HYIP plans may run for a few days, several weeks, or a longer fixed period. The duration determines when the program claims to pay returns or return the original deposit.
Look for wording such as:
- Daily for 30 days: The plan advertises regular payments during a 30-day period.
- After 14 days: Payment is scheduled at the end of the stated term.
- Principal returned at the end: The website claims to return the original deposit when the plan expires.
- Lifetime plan: The program advertises payments without a clearly defined end date.
Do not assume that the original deposit will be returned simply because the plan says so. The operator may fail to pay, change the terms, or stop operating.
3. Find Out Whether the Principal Is Included
One of the most important details is whether the advertised payout includes the original deposit.
Consider a hypothetical example: a website advertises a total payout of $150 on a $100 deposit.
That figure could mean different things:
- $150 in total, including the original $100.
- $150 in profit, plus the original $100.
- A projected amount that depends on reinvestment or other conditions.
These scenarios produce very different results. Read the plan description and terms carefully, and do not assume the most favorable interpretation.
If the website does not explain whether the principal is included, the actual payout structure is unclear.
4. Compare Minimum and Maximum Deposits
Investment plans often have deposit limits. A basic plan might accept $10, while another requires $500 or more.
A higher minimum deposit does not mean that a plan is safer or more profitable. Similarly, a program offering several investment levels is not necessarily more legitimate than one with a single plan.
Before considering any deposit, check:
- The minimum and maximum amounts.
- Whether the limits differ by payment method.
- Whether additional deposits are required to unlock withdrawals.
- Whether the website encourages you to upgrade to a higher tier.
- Whether advertised bonuses come with restrictive conditions.
Be particularly cautious if the operator pressures you to deposit more money to access funds that are supposedly already yours.
5. Read the Withdrawal Rules
A plan may advertise frequent payouts, but the withdrawal policy determines how investors can actually request their money.
Look for details about:
- Minimum withdrawal amounts.
- Processing times.
- Withdrawal fees.
- Supported payment methods.
- Verification requirements.
- Restrictions on withdrawing the original deposit.
- Conditions attached to bonuses or reinvested earnings.
Check whether the withdrawal rules are consistent across the website. If the promotional page promises instant withdrawals but the terms allow lengthy delays, that inconsistency deserves attention.
Never assume that a displayed account balance means the funds are available to withdraw.
6. Understand Reinvestment Options
Some HYIP websites offer an option to reinvest earnings instead of withdrawing them. This may be described as compounding, reinvestment, or automatic renewal.
Reinvestment can make projected account balances grow quickly on paper. However, it also leaves more money exposed to the same operator and may make it harder to withdraw funds before the program fails.
For example, a dashboard might show an increasing balance while the investor has not received any money in an external wallet or bank account.
A growing balance is not proof of a real profit. Actual withdrawals, where possible, still do not establish that a program is sustainable or safe.
7. Check Referral Commissions Separately
Many HYIP programs advertise referral rewards for inviting new participants. The commission may be a percentage of a referral’s deposit or may depend on the referral’s activity.
Read the referral terms separately from the main investment plan. Determine what triggers a commission, whether it can be withdrawn, and whether additional conditions apply.
A strong focus on recruitment is a reason for extra caution, especially if the program provides little verifiable information about its actual business activities.
Referral payments do not prove that an investment generates legitimate revenue.
8. Look for Fees and Hidden Conditions
An advertised return may not reflect what a participant can actually receive. Fees, restrictions, and special conditions can affect the final amount.
Check for:
- Deposit and withdrawal charges.
- Currency conversion costs.
- Minimum account balances.
- Fees for early withdrawal.
- Conditions for bonus eligibility.
- Rules that allow the operator to suspend or reject payments.
Read the full terms rather than relying only on the investment-plan table. If important conditions are missing or vague, do not assume that the operator will resolve the uncertainty in your favor.
9. Identify Warning Signs in the Plan
Certain features deserve particular attention when evaluating a HYIP website.
Unusually high returns: Large daily or weekly percentages without a clear, verifiable source of income are a serious warning sign.
Guaranteed profits: Claims that investors cannot lose money are not credible assurances of safety.
Unclear business model: The website does not explain how it generates enough revenue to support the advertised payouts.
Pressure to deposit quickly: Countdown timers, limited-time offers, or urgent messages encourage decisions without adequate research.
Changing terms: The operator changes payout rules, adds unexpected conditions, or delays withdrawals without a convincing explanation.
Unverifiable company information: Ownership, registration, location, or relevant regulatory status cannot be independently confirmed.
No single feature tells the whole story, but several of these warning signs together should make you especially cautious.
10. Calculate the Potential Loss, Not Just the Return
Investment-plan tables focus attention on what participants might receive. A more useful question is how much you could lose if the program stops operating.
Suppose you deposit $100 into a program advertising an attractive return. If withdrawals become unavailable, you may lose the entire $100, regardless of the profit shown on the dashboard.
Do not borrow money, use emergency savings, or deposit funds needed for rent, bills, or other essential expenses into a high-risk program.
Also avoid treating a small successful withdrawal as proof that a larger deposit will be safe. Payment behavior can change, and earlier payouts do not guarantee future access to funds.
How to Compare Two HYIP Investment Plans
When comparing plans, use the same checklist for both rather than choosing the one with the highest advertised percentage.
| What to compare | What to look for |
|---|---|
| Advertised return | Is the calculation clearly explained? |
| Investment term | Is the end date defined? |
| Principal | Is the original deposit included in the payout? |
| Withdrawals | Are the rules, fees, and restrictions clear? |
| Business model | Is there independently verifiable evidence of revenue? |
| Company details | Can the operator and its claims be checked? |
| Risk | Could you afford to lose the entire deposit? |
A plan with more detailed terms is easier to understand, but transparency alone does not make a HYIP safe. Even a professionally designed website can present misleading claims.
Final Thoughts
Learning how to read HYIP investment plans helps you understand advertised percentages, payment schedules, deposit limits, and withdrawal conditions. It can also help you spot inconsistencies before committing money.
The most important point is that understanding a plan does not eliminate the underlying risk. HYIPs are highly speculative, and some may be Ponzi schemes or other fraudulent operations. Promised returns should never be treated as reliable income.
If you are researching online investment opportunities, you can also explore our Investment Programs to review available information and compare program claims critically.
Disclaimer: This article is for educational and informational purposes only. It is not financial or investment advice. HYIP programs carry a high risk of loss, including the possible loss of your entire deposit. Always conduct independent research before making financial decisions.